High Yield: Attractive Income, Expanding Opportunities
Strong economic growth and resilient corporate fundamentals continue to support high yield. With all-in yields near their highest levels in more than two decades, investors may be able to generate attractive income while remaining disciplined on credit quality.
High yield markets remain well supported. In the U.S., consumer spending, fiscal support and significant AI-related investment have contributed to robust economic activity, while longer-term inflation expectations have remained relatively stable.
This suggests that the recent rise in government bond yields reflects stronger growth more than a material deterioration in the inflation outlook.
For credit investors, this is a favorable combination.
- Healthy earnings are helping companies manage leverage, maintain or improve interest coverage and absorb higher borrowing costs.
- Most borrowers have adjusted to a higher cost of capital, unlike in 2022, when many faced a rapid transition from near-zero rates
- Incrementally higher interest expense may weigh on cash flows, but it is unlikely to fundamentally change the credit profile of a typical issuer as long as earnings remain strong
That said, the picture is not uniformly positive. Higher rates continue to pressure housing and other rate-sensitive sectors. The consumer also warrants close attention, given the role that rising asset values have played in supporting spending. A key distinction going forward will be balance sheet flexibility. Companies with healthy earnings and manageable capital structures should be better positioned to navigate a more challenging environment than borrowers with less room for error.
Fundamentals: Healthy Balance Sheets, Growing Dispersion
High yield fundamentals remain healthy. Earnings growth has extended beyond the largest technology companies, while many issuers continue to generate sufficient cash flow to service their debt.
The higher-quality composition of the market provides an additional source of stability. BB issuers represent a significantly larger share of the global high yield bond market than they have historically (62%), while CCC exposure has declined (7%). This higher-quality mix should help limit the effect of stress among weaker borrowers.1 It’s a similar story in loans, where exposure to CCCs has declined in both the U.S. (7%) and Europe (4%) over time.2
Beneath the surface, sector and issuer-level dispersion is becoming more pronounced.
- In the U.S., housing conditions remain challenging, but many homebuilders entered this period with solid balance sheets and relatively conservative capital structures. Greater pressure is evident among certain highly leveraged building products companies whose debt loads were established against a more favorable operating backdrop.
- In Europe, chemicals and automotive companies face competitive and structural pressures, including weaker industrial demand and competition from lower-cost producers. However, many began with comparatively strong credit profiles, suggesting a deterioration may appear first through a gradual rise in leverage or wider spreads, rather than widespread defaults.
AI: A Growing Influence on Credit Markets
AI is an increasingly important consideration across credit markets.
The infrastructure buildout will continue to require substantial investment in data centers, power generation, transmission networks and related assets, creating significant financing needs across public and private markets. At the same time, AI is reshaping competitive dynamics across a much broader range of industries, raising questions about how well individual companies will fare.
For high yield investors, the infrastructure buildout may create opportunities. Some AI-related borrowers appear willing to pay relatively high financing costs to secure the capital necessary to keep projects moving, while recent weakness in parts of the data center market has created potentially more attractive entry points.
However, the scale and pace of the buildout introduces several risks:
- Execution risk remains significant, particularly as projects become larger and more complex
- A sustained increase in issuance could put pressure on the prices of existing debt and require new deals to offer higher yields to attract investors
- Political and regulatory considerations may become more prominent as data center development places greater demands on power systems and local infrastructure
Figure 1: AI-Related Gross Supply ($BN) and Its Share of Total Issuance (YTD 2026)
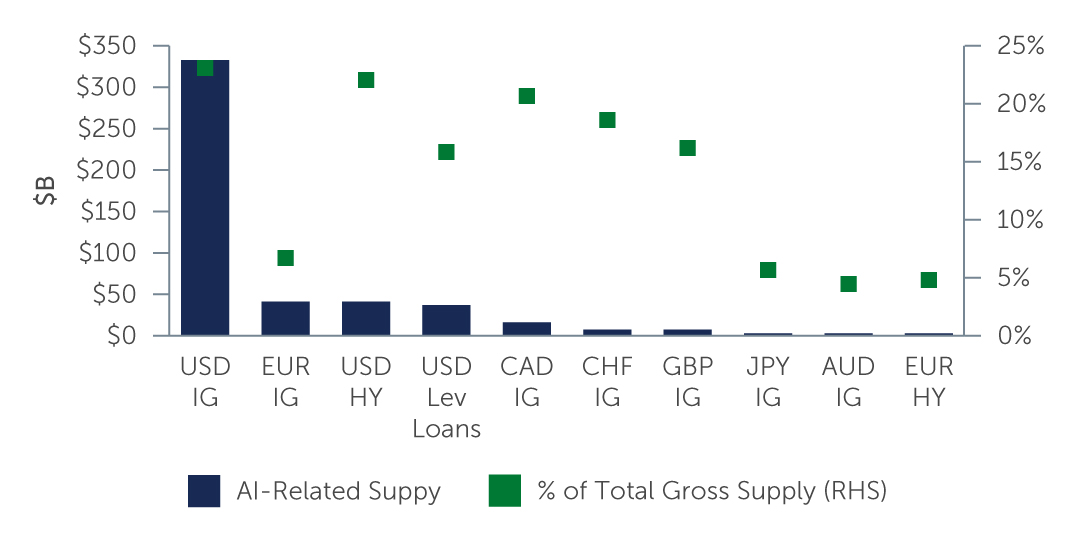 Source: For non-USD markets, we use USD-equivalent figures. Excludes undrawn credit facilities and revolvers. For AI-adjacent sectors (Energy & Utilities, Oil & Gas, Construction, Machinery, Chemicals, Metal & Steel), we assume only 30% of gross issuance is AI-related. As of July 25, 2026.
The implications extend beyond the companies financing the infrastructure itself. Travel platforms, insurance brokers, price-comparison services and other businesses that intermediate consumer decisions could face increased pressure as AI makes it easier to research options and compare providers directly. The impact will vary by company, making it increasingly important to assess how AI could affect competitive positions, pricing power and cash flows.
Exposure to the AI investment cycle also varies across regions. European high yield currently has less direct exposure to AI-related sectors and the data center buildout than the U.S. market. This difference in market composition may provide a way to manage concentration as AI-related issuance continues to grow and its effects become more pronounced.
The Opportunity: Income Without Reaching for Risk
With yields at current levels, investors can generate attractive income without reaching aggressively down in quality. This is creating opportunities across both high yield bonds and loans, while allowing investors to remain selective and disciplined on credit risk.
Bonds look particularly attractive in the current environment. Their combination of higher income and relatively short duration may be especially valuable in a market where economic growth remains robust and rates could stay elevated. Shorter duration helps limit sensitivity to further rate increases, while current yields provide a meaningful foundation for returns. Within the bond market, shorter-maturity bonds in particular can provide attractive carry without requiring investors to assume significant interest-rate risk.
Loans also continue to offer attractive income and may be well positioned if inflation and policy rates remain elevated. However, with much of the market trading around or above par, credit selection remains important given the more limited potential for price appreciation.
While the current environment provides multiple ways to capture income, tight spreads mean broad market exposure is unlikely to be sufficient on its own. The more compelling opportunities may come from identifying higher-quality issuers that offer attractive all-in yields and adding risk where market technicals have caused prices to diverge from underlying fundamentals.
The Bottom Line
High yield is heading into the fourth quarter a position of strength. Resilient growth and healthy corporate fundamentals continue to support credit, while higher yields are creating attractive income opportunities across the asset class.
The landscape may become more complex as AI-related financing brings new issuance and technology reshapes individual sectors and business models. That should create opportunities alongside greater dispersion, favoring investors who can remain selective and take advantage when market pricing moves away from fundamentals.
1. Source: ICE BofA Non-Financial Developed Markets High Yield Constrained Index. As of August 31, 2026.
2. Sources: Barings; S&P UBS Leveraged Loan Index; S&P UBS Western European Leveraged Loan Index. As of June 30, 2026.
26-6001414