Public Fixed Income

Anchored by Income: The Resilience of Broadly Syndicated Loans

October 2026 – 6 min read

Contractual income, a deep and stable institutional investor base and diversification benefits have helped loans deliver resilient performance across a wide range of market environments, reinforcing their role as a strategic portfolio allocation.

Markets have navigated a challenging backdrop in recent years, shaped by geopolitical tensions, shifting trade policies and the evolving and uncertain implications of artificial intelligence. Yet amid these crosscurrents, the broadly syndicated loan market has remained notably resilient. Over the past decade, loans have delivered both positive returns and strong risk-adjusted performance relative to other liquid fixed income sectors (Figure 1)—driven by the asset class’s contractual income, deep institutional investor base and lower volatility profile.

Figure 1: 12-Month-Return Sharpe Ratio by Asset Class
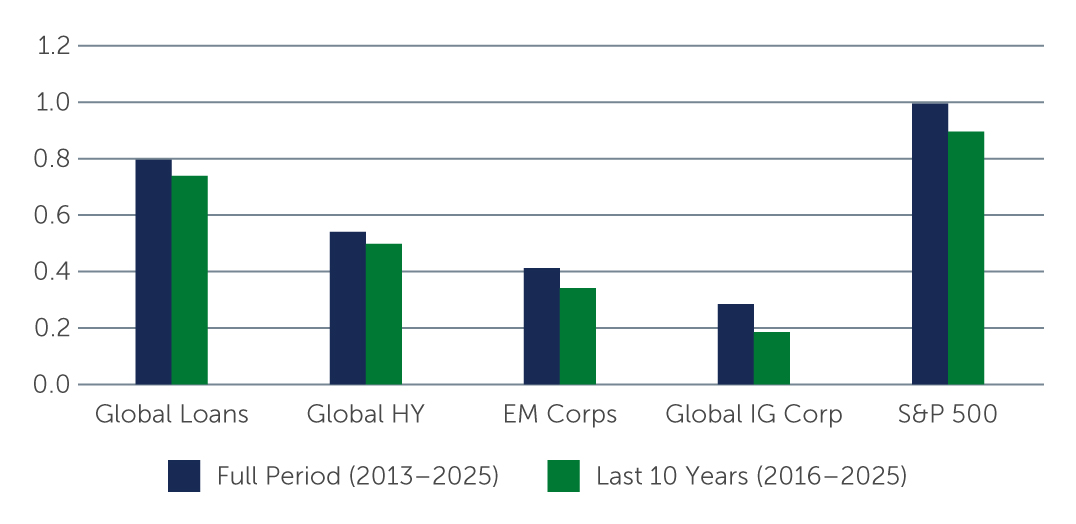
Figure 1: 12-Month-Return Sharpe Ratio by Asset ClassSource: S&P UBS Global Leveraged Loan Index, ICE BofA Non-Financial Developed Markets High Yield Constrained Index (HNDC), J.P. Morgan CEMBI Broad Diversified Index, Bloomberg Global Aggregate Index, S&P 500 Index. As of December 2025. PAST PERFORMANCE IS NOT NECESSARILY INDICATIVE OF FUTURE RESULTS.

Structural Advantages of Loans

There are several defining characteristics of the broadly syndicated loan asset class that have contributed to its strong performance over time, despite periods of market volatility and shifting macroeconomic conditions.

26-5931539
Want to read the full article?

View PDF
Headshot of Chris Sawyer smiling at the camera.

Chris Sawyer

Head of European High Yield

Amanda Koelzow

Senior Director, Client Portfolio Management

Important Information

The document is for informational purposes only and is not an offer or solicitation for the purchase or sale of any financial instrument or service. The material herein was prepared without any consideration of the investment objectives, financial situation or particular needs of anyone who may receive it. This document is not, and must not be treated as, investment advice, investment recommendations, or investment research.

In making an investment decision, prospective investors must rely on their own examination of the merits and risks involved and before making any investment decision, it is recommended that prospective investors seek independent investment, legal, tax, accounting or other professional advice as appropriate.

Unless otherwise mentioned, the views contained in this document are those of Barings. These views are made in good faith in relation to the facts known at the time of preparation and are subject to change without notice. Parts of this document may be based on information received from sources we believe to be reliable. Although every effort is taken to ensure that the information contained in this document is accurate, Barings makes no representation or warranty, express or implied, regarding the accuracy, completeness or adequacy of the information.

Forecasts in this document reflect Barings’ market views as of the preparation date and may change without notice. Projections are not guarantees of future performance. The value of investments and any income may fluctuate and are not guaranteed by Barings or any other party. Examples, portfolio compositions, and investment results shown are for illustrative purposes only and do not predict future outcomes. Actual investments may differ significantly in size, composition, and risk. No assurance is given that any investment will be profitable or avoid losses. Currency exchange rate fluctuations may impact investment value.

Investments involve risks, including potential loss of principal. Past performance is not indicative of future results. Investors should not only base on this document alone to make investment decision.

This document is issued by Baring Asset Management (Asia) Limited. It has not been reviewed by the Securities and Futures Commission of Hong Kong.